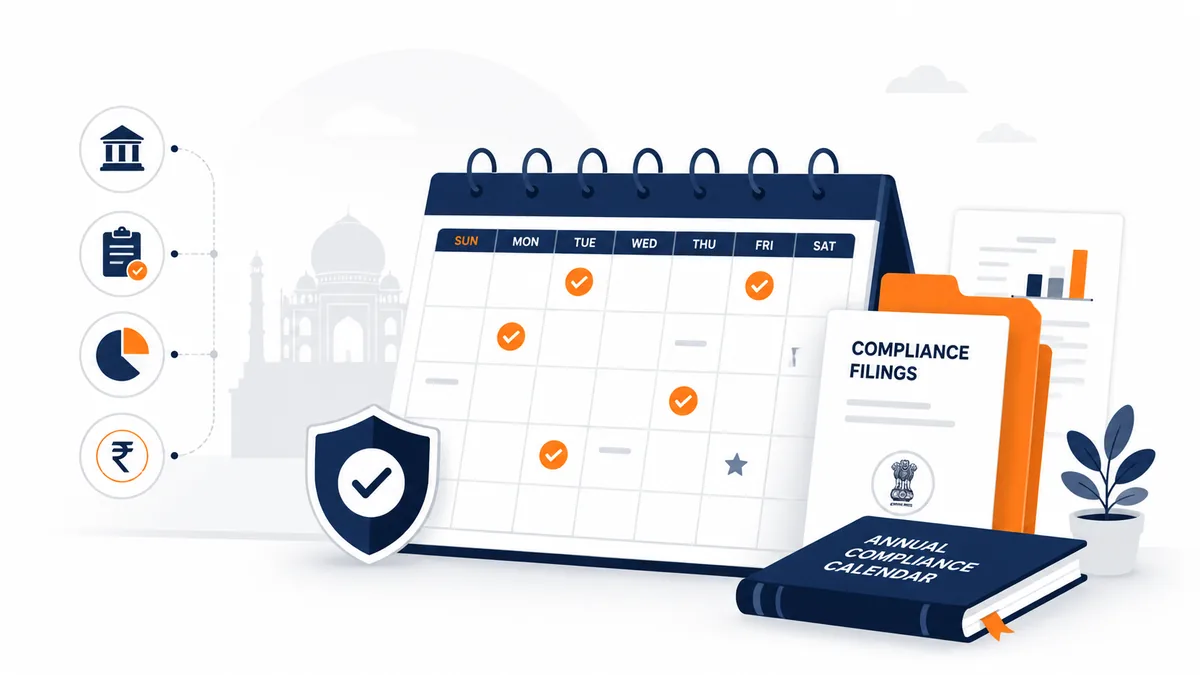
Incorporation and entry-level registrations get a foreign-owned company up and running. Staying in good standing, however, is a recurring discipline. India’s compliance calendar runs on monthly, quarterly, and annual rhythms, and missed deadlines carry penalties and, over time, reputational and operational risk. This article frames the recurring obligations so finance leaders can build them into a routine.
Monthly and quarterly obligations
Several obligations recur frequently. Tax deducted at source on payments typically must be deposited and reported periodically. Where the company is registered for indirect tax, periodic returns and payments fall due. Payroll-linked statutory contributions also follow a regular cycle once the company has employees.
Annual corporate filings
Each year a company must hold its annual general meeting, have its financial statements audited, and file its financial statements and annual return with the registrar. The board must also meet at the minimum prescribed frequency through the year, with proper records maintained.
Annual tax obligations
The company files its annual income tax return and, where applicable, undergoes tax audit. Advance tax may be payable in instalments through the year, and transfer pricing documentation can apply where the company transacts with related parties abroad — a common situation for foreign-owned entities.
Foreign investment and FEMA reporting
Foreign-owned companies have periodic reporting tied to foreign holdings, including an annual return on foreign liabilities and assets where applicable. Any further capital infusion, share transfer, or downstream investment generally triggers its own event-based reporting.
Event-based filings
Beyond the calendar, certain events trigger filings whenever they occur — changes in directors, registered office, capital, or shareholding, and the creation or satisfaction of charges. Tracking these alongside the periodic calendar prevents gaps.
Building the discipline
The practical answer is a single, owned compliance calendar with deadlines, responsible parties, and reminders, supported by a professional network handling the filings. For finance leaders managing India remotely, this turns a fragmented set of obligations into a predictable routine, subject to professional review. It also creates an audit trail: when the parent’s auditors or a prospective acquirer ask how the Indian entity has been administered, a documented calendar with evidence of timely filings is far more reassuring than a scramble to reconstruct the record after the fact.
Frequently asked questions
What happens if a filing deadline is missed? Late filings generally attract penalties and additional fees, and repeated lapses can escalate. A proactive calendar is the practical safeguard.
Do foreign-owned companies have extra reporting? Yes — foreign holdings bring additional FEMA-related reporting, both annual and event-based, on top of standard corporate and tax filings.
Can compliance be managed remotely from abroad? Yes. With a coordinated professional network and a shared calendar, foreign leadership can oversee India compliance without being on the ground.
Talk to our India desk
A reliable compliance calendar keeps your Indian entity in good standing and frees leadership to focus on the business. To set up a coordinated, year-round compliance routine, book a strategy call with our India desk.
Disclaimer: general information only, not advice. Rules, rates, and thresholds change and are subject to applicable law and professional review. Confirm specifics with qualified professionals before acting.
Discuss this topic with our India desk
Get a practical read on how this applies to your company's India plans — in a 30-minute call with a senior advisor.