The period immediately after incorporation is when foreign-owned companies are most exposed to missed obligations. The certificate of incorporation arrives, but a cluster of registrations and reporting requirements follows quickly — some time-bound. This article lays out the entry-level compliances so newly formed companies can sequence them correctly.
Tax registrations
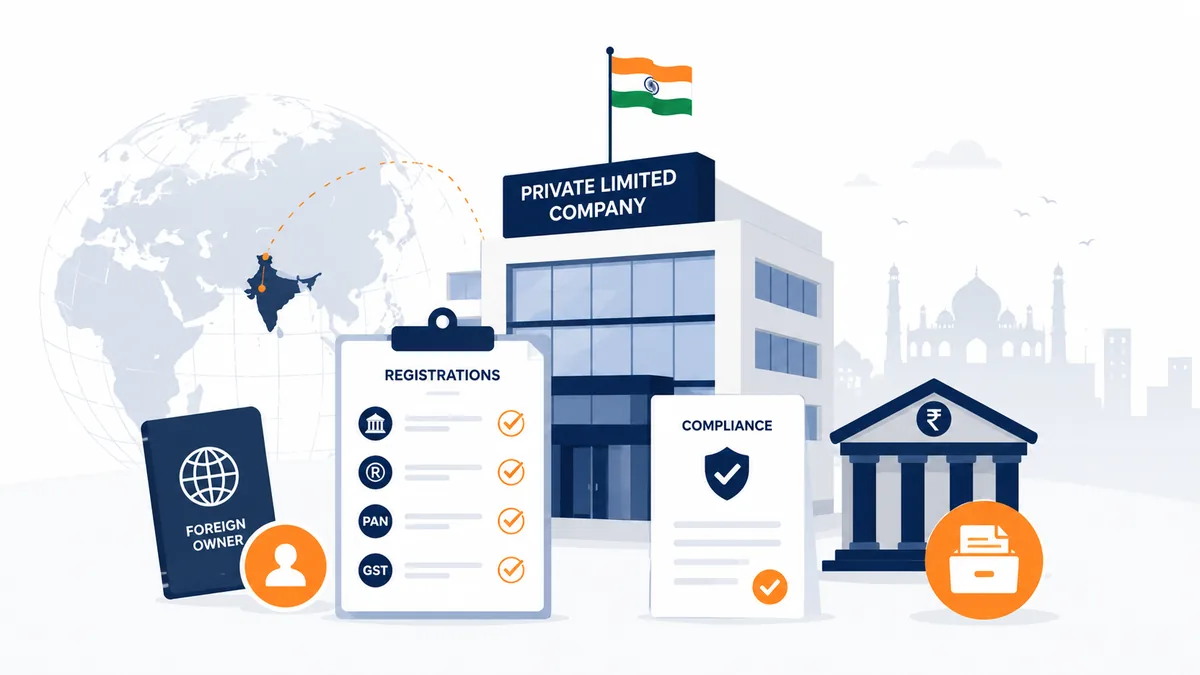
A new company generally needs core tax registrations to operate and transact — including registrations that enable it to deduct tax at source on payments and to charge and remit indirect tax once it crosses applicable thresholds.
Foreign investment reporting
When the foreign parent remits subscription capital, the inflow and allotment of shares typically must be reported to the regulator within prescribed timelines. This is a common area for slip-ups because the clock starts on the inflow, not on convenience.
Banking and capital
The company needs an operating bank account, and the parent’s subscription capital must be brought in through banking channels and documented. Banks apply their own due-diligence requirements on foreign-owned entities, so early engagement helps avoid hold-ups.
Labour and social security enrolments
Once the company begins hiring, it generally must enrol under applicable labour and social security schemes and register under relevant state legislation. The applicability and timing often depend on employee headcount and the states of operation.
Statutory housekeeping
In its first phase, a company also addresses governance basics: appointing its auditor, holding its first board meeting, issuing share certificates, and maintaining statutory registers. These are not optional and form the foundation of a clean compliance record.
Sequencing it sensibly
The practical approach is to treat the first phase as a project with owners and deadlines: tax registrations and banking early, foreign investment reporting tied to the capital inflow, and labour enrolments as hiring begins. A coordinated calendar prevents the common pattern of discovering a missed filing months later. For foreign leadership overseeing the entity from abroad, it also gives a single reference point — a clear view of what has been completed, what is pending, and who is responsible — rather than a series of disconnected requests to local advisors. Establishing that structure in the first weeks tends to save considerable time and avoidable cost across the entity’s first year.
Frequently asked questions
Which compliances are time-bound right after incorporation? Several are, including foreign investment reporting tied to capital inflow and certain governance steps. The specifics depend on current rules.
Does a new company need indirect tax registration immediately? Often only once it crosses the applicable turnover threshold or undertakes certain transactions, though some businesses register from the outset.
When do labour registrations apply? Typically once hiring begins and headcount or other thresholds are met; this varies by scheme and state.
Talk to our India desk
Getting the entry-level compliances right protects the company from early, avoidable penalties. To set up a coordinated first-phase compliance plan, book a strategy call with our India desk.
Disclaimer: general information only, not advice. Rules, rates, and thresholds change and are subject to applicable law and professional review. Confirm specifics with qualified professionals before acting.
Discuss this topic with our India desk
Get a practical read on how this applies to your company's India plans — in a 30-minute call with a senior advisor.